Flagler & Volusia Homes for Sale Fell 15% While the Nation's Piled Up
Flagler & Volusia County Real Estate Market Update — August 2026
Two minutes on what the Flagler and Volusia housing market did in August, why it went the opposite direction from the national numbers, and one thing to check before you compare a builder's rate to a resale.
The numbers at a glance
| Measure | August 2026 | vs. last August |
|---|---|---|
| Homes for sale | 4,866 | down 15% |
| Homes sold | 983 | up 8% |
| Middle price | $350,000 | up 3% |
| Months of supply | 5 | down from 6.3 |
| Sold vs. asking | 98% | — |
| Days to sell | 83 | down from 86 |
Fewer homes for sale means less competition if you're selling, and less to choose from if you're buying.
Every arrow is the same colour. The arrow shows which way the number moved, not whether that's good or bad, because that depends on whether you're buying or selling.
The written version
The national housing story doesn't match Flagler & Volusia's.
Nationally this month: mortgage rates hit 6.95%, the highest since January 2025, and the Fed raised its policy rate for the first time in nine months. Asking prices have now fallen for ten straight months while active inventory climbed 3.6% year over year.
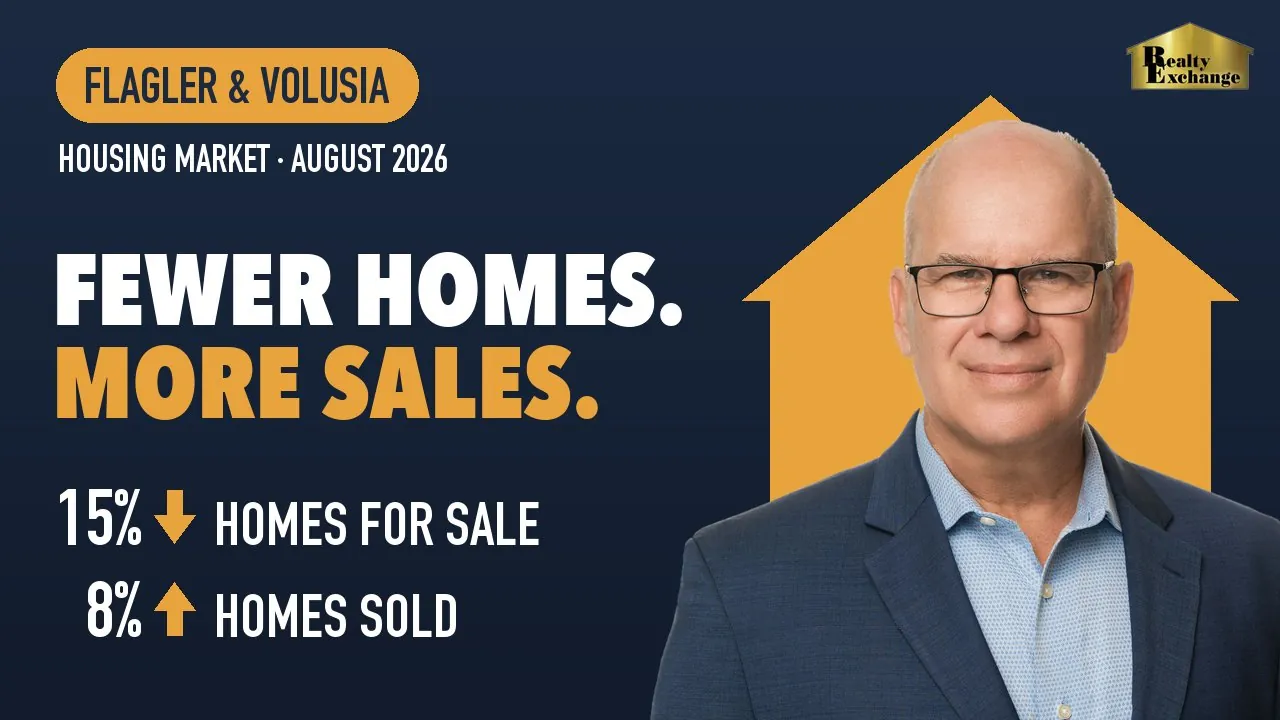
Flagler and Volusia did the opposite. Resale inventory fell 15% year over year to 4,866 active listings. Closed sales rose 8% to 983. The median sale price reached $350,000, up from $340,000 last August. Months of supply tightened from 6.3 to 5, more than a month of leverage moving back toward sellers in a single year.
We are not an outlier in this state. Realtor.com names Jacksonville (down 17%) and Miami (down 15%) as the steepest drops in homes for sale among the 50 largest U.S. metros. At 15%, we're right there with them.
Why prices only moved 3%.
Two forces, pulling opposite ways.
Supply is scarce because 88% of homeowners with a mortgage still hold a rate below 6%. With the market near 7%, those owners are not listing.
Pricing is capped because of new construction. Roughly one in seven new-home listings nationally now advertises a rate buydown, averaging 3.92%. When Realtor.com measured that, the going mortgage rate was 6.67%, and the difference was worth about $600 a month, or $112,000 in buying power. Rates have since climbed to 6.95%, which makes that gap even wider. Much of that inventory never enters the MLS, so it appears in none of the figures above, yet it competes directly with every resale listing in this county.
Month over month the market looks flat: sales up under one percent, median unchanged, days on market up from 76 to 83. That comparison is misleading. July was an unusually fast month at 76 days, well ahead of last July. August at 83 days is still faster than last August's 86. Nothing slowed down. The prior month was simply a standout.
For anyone holding property here: if you sell, you'll face less competition than the national numbers suggest, and prices have held firm. For agents: the shortage here is homes to sell, not buyers.
Dave's Hot Take & Cool Tip for August
Everybody reads inventory at a decade high and braces for 2008. I sold over 1,000 bank-owned homes in that cycle. This is not that. Then we had inventory and no buyers. Now we've got buyers and no inventory.
That 3.92% rate? Read the terms. Most are temporary buydowns and the payment climbs later. Know what's in the contract, and you'll win the listings against a builder all day.
Dave Petkovsek, from the August 2026 video
Prefer to read it? Show transcriptHide transcript
Every word Dave says in the August 2026 video.
Thanks for checking out this month's Market Update & More. Be sure to stick around for my Hot Take and Cool Tip for the month.
Mortgage rates just hit 6.95%, the highest since January of last year. The Fed raised rates for the first time in 9 months, and nationally, asking prices have fallen 10 months running while inventory keeps climbing.
I'm Dave Petkovsek with Realty Exchange, and now here's what's happening in Flagler and Volusia.
Inventory is down 15% from last August, and sales are up 8%. Median at $350,000, up from $340,000. Absorption tightened from 6.3 months to 5.
Nationally, supply is piling up. Here, it is draining.
Two reasons. 88% of homeowners with a mortgage are still sitting under 6%. At 7%, they don't move, and that's your missing inventory.
And rates: builders are advertising 3.92% against 6.95%. That's $600 a month and $112,000 in buying power. No resale listing competes with that on payment. That's what's holding us to 3%.
Everybody reads inventory at a decade high and braces for 2008. I sold over 1,000 bank-owned homes in that cycle. This is not that. Then we had inventory and no buyers. Now we've got buyers and no inventory. Jacksonville's down 17%. Miami's down 15%. Those are the steepest drops in the country, and we're right there with them.
My Cool Tip: that 3.92% rate? Read the terms. Most are temporary buydowns and the payment climbs later. I teach the contract class for the Florida Association of Realtors. Know what's in the contract, and you'll win the listings against a builder all day.
That's your update. We'll see you next month.
Every Market Update & More
Call me.
Buying, selling or managing a portfolio in Flagler or Volusia County? Call me, and we'll talk it through.
Asset managers: I've handled bank-owned and distressed property in this market since the 2008 cycle. If you need a local read you can trust, call me.
- Phone386-627-3182
- EmailDave@RealtyExchangeFL.com
- OfficeRealty Exchange · Palm Coast, Florida